
Credit Genie
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
Credit Genie - Screenshots
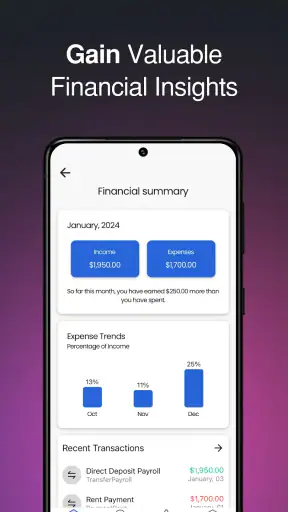
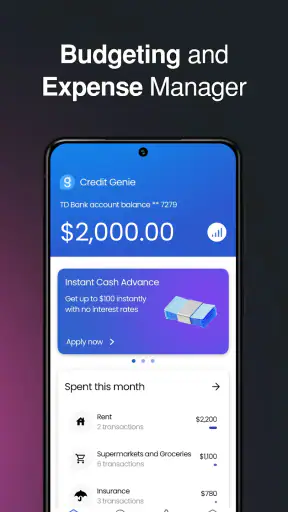
Pros
- Quick access to cash advances without a traditional credit check.
- Clear repayment dates help users plan upcoming withdrawals.
- Useful alerts can help prevent missed payments or overdraft fees.
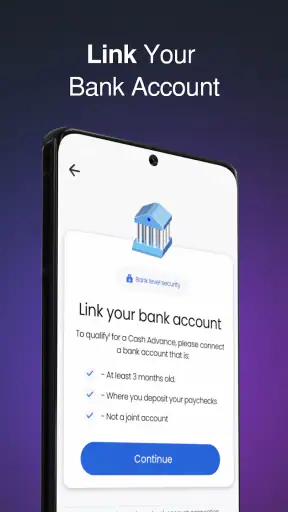
- Simple application process completed entirely from a mobile device.
- May help cover small emergency expenses between paychecks.
Cons
- Cash advances may include subscription fees or optional express-transfer charges.
- Eligibility and advance limits can vary significantly between users.
- Repayment is typically automatic
- which may strain a tight budget.
- Not available in every state or to all types of bank accounts.
- Frequent use can create a cycle of borrowing between paychecks.
Credit Genie - Description
- App Name
- Credit Genie
- Package Name
- com.creditgenie.app
- Developer
- Creditly Corp
- Category
- Finance
- Last Updated
- Oct 18, 2021
- Version
- 3.5.0
Managing money on a shared phone is rarely as simple as opening one app and handing it to everyone in the household. A budgeting tool may be useful for one person but awkward for a couple, a parent and an older teenager, or housemates who split everyday costs. I found Credit Genie most interesting in that context because it is positioned as a broad finance app rather than a narrow calculator or a single-purpose expense tracker. It is free to install, aimed at Everyone, and developed by Creditly Corp.
My overall impression is that it works best when one person takes responsibility for the financial overview and uses the app as a regular checkpoint, rather than treating it as a shared family ledger with automatic boundaries between users. That distinction matters. The app can fit into household routines, but the quality of the experience depends heavily on who is using it, what information they are comfortable seeing, and how clearly everyone agrees on what the app is for.
How Credit Genie fits into a shared household routine
A realistic use case: one phone, several financial decisions
Imagine a household where one adult handles recurring bills, another contributes toward groceries, and a teenager is learning how spending affects available money. In that situation, I would not give everyone unrestricted access to one financial workspace and hope the arrangement sorts itself out. I would first decide whether the app is being used for personal credit-related organization, a household overview, or simply a place for one person to check their own financial position.
That small decision prevents a common mistake: assuming that a finance app becomes a family tool just because several people discuss the same bills. Shared finances and shared app access are not the same thing. If the app is installed on a common tablet or a phone passed around the home, conversations about privacy become just as important as the app’s practical functions.
For my own household-style test, the most sensible workflow would be to choose one primary user, review the information privately, and then bring only the useful conclusions into a family conversation. For example, the person managing the monthly budget could use Credit Genie to organize their own financial checks, then tell the household that a subscription needs reviewing or that a planned purchase should wait. That is safer and less confusing than letting everyone edit or inspect the same setup without an agreed purpose.
The app’s broad finance focus is helpful here because it can sit near several money habits at once. It is not limited to a simple spending diary in the way some basic alternatives are. At the same time, that wider scope means I would spend a little time learning where each action belongs before making it part of a shared routine. A household app needs clarity more than a long list of possibilities.
Why the free entry point matters
Credit Genie is available at no cost, which makes it easier to try without asking the whole household to commit money first. That is especially useful when people have different levels of interest. One person can test whether the workflow is comfortable, while others can decide whether they want to participate in discussions without being pushed into installing it immediately.
Still, free does not automatically mean frictionless. The real cost can be attention: remembering to open the app, checking whether the information is still relevant, and deciding who is responsible for acting on what it shows. I would judge it over a normal household week rather than after a single launch. If nobody knows what to do after checking the app, the problem is not solved by having another finance tool on the phone.
What I would not use it for
I would not treat it as a replacement for a bank’s own secure account access, nor would I use one unlocked shared device as a substitute for separate personal boundaries. Banking apps are generally the right place for direct account actions and sensitive authentication. A general finance app can support awareness and organization, but it should not encourage casual access to private financial details.
I would also avoid presenting it to a child as a magic answer to money management. A young user may understand a visible balance or a spending decision, but that does not mean they should see an adult’s complete financial picture. The app’s Everyone age classification makes it broadly suitable from a content perspective, yet age suitability and household permission are different questions.
Setting boundaries before the first session
Before using Credit Genie around other people, I would establish four simple boundaries: whose information is being viewed, who holds the device, what the app is meant to help with, and what decisions remain private. These are not complicated rules, but they prevent an ordinary money check from turning into an argument about access.
For a couple, the right arrangement might be a joint conversation after one person reviews the household position. For housemates, it may be better to keep personal finances separate and discuss only agreed shared expenses. For a parent and teenager, I would use the app as a teaching prompt rather than an open window into the parent’s finances. Each arrangement needs a different level of visibility.
The most important setup choice is not a button inside the app; it is deciding what should remain outside the shared screen. That is the practical boundary I would establish before entering information or letting someone else explore the app.
Account boundaries on a shared device
A shared phone creates a particular risk: people often assume that anything already open is fair to browse. I would avoid leaving a finance session visible on a communal device and would not pass the phone around while personal information is displayed. If several household members use the same device, each person should understand that the app is not automatically a multi-user family workspace simply because the hardware is shared.
I would also keep the app’s role separate from the device owner’s role. The person who owns the phone should not automatically become the person who speaks for every household member. Conversely, the person who manages bills should not assume that others want their personal financial details entered into a common place. Clear consent is more useful than an improvised arrangement.
This is where Credit Genie may be a better fit for an individual coordinator than for a large household. One responsible user can maintain a consistent routine, while the rest of the family receives decisions or reminders through ordinary conversation. If your goal is truly separate profiles, individual permissions, or a detailed shared ledger, I would compare it with a dedicated household budgeting service before settling on this app.
Making coordination practical instead of intrusive
Finance discussions often fail because they happen only when something goes wrong. I would use the app as a prompt for short, scheduled conversations: what needs paying, which shared cost changed, and whether a planned purchase still makes sense. The app can support that rhythm, but it cannot replace agreement between the people involved.
A useful approach is to give each person a defined responsibility. One person reviews recurring obligations, another checks shared spending, and a teenager might track a personal saving goal outside the adult account details. Even if Credit Genie is used by only one person, the household can still benefit from the conclusions. This avoids the false choice between total access and no coordination at all.
Another practical tip is to separate “information” from “approval.” Seeing that a cost exists does not mean everyone has approved a new purchase. I would discuss proposed changes separately, especially when money is tight. This keeps the app from becoming an authority in family decisions and makes it clear that the final choice belongs to the people responsible for the money.
Where it differs from ordinary alternatives
The usual alternatives in this category tend to fall into three groups: a bank’s own app, a manual spreadsheet, or a dedicated budgeting service. A bank app is normally stronger for direct account access and transaction confirmation. A spreadsheet offers more control over categories and sharing, but it demands more manual upkeep. A specialist budgeting service may provide a more structured household workflow, depending on the product and the family’s needs.
Credit Genie sits in a more approachable middle ground for someone who wants a finance-focused mobile experience without building a system from scratch. Its appeal is convenience and breadth, not the flexibility of a spreadsheet or the institutional role of a bank app. I would choose it when I wanted a single place to begin reviewing my financial situation, but I would not assume that its broad positioning automatically makes it the best tool for detailed family accounting.
The trade-off is worth understanding before a household adopts it. A simple app can encourage regular checking because it feels less like administrative work. However, if your family needs carefully separated accounts, edit histories, formal approvals, or a precise record of who paid each shared bill, a more specialized solution may be better. Credit Genie is more convincing as a personal finance companion that can inform household coordination than as a complete family operating system.
Age, trust, and the right level of explanation
Because the content rating is Everyone, I would feel comfortable discussing the app with a teenager or showing a younger family member the general idea of financial planning. I would still keep the lesson narrow. A child can learn why a purchase affects a plan without being shown private balances, credit information, or adult obligations.
With older teenagers, I would focus on interpretation rather than surveillance. Ask what they think a financial figure means, what decision it might influence, and what information should stay private. That turns the app into a conversation starter instead of a monitoring device. Trust grows when the young person knows the purpose of the exercise and is not surprised by hidden access.
For adult housemates, consent is even more direct. I would never add someone else’s financial information merely because we share rent or utilities. The cleanest arrangement is often for each person to manage their own details and contribute only the agreed totals. If a housemate does not want to use the app, that should not prevent the others from coordinating through a simple shared note or conversation.
What the current release means for trying it
The current release is version 3.5.0, and the app requires Android 10 or later. That makes the operating-system requirement relevant for households with an older spare phone or a hand-me-down device. Before planning a shared installation, I would check the phone’s software level rather than assuming that every Android device can run it.
This is a small but realistic source of friction. A household may have one newer phone used by an adult and an older device intended for a teenager or shared kitchen use. If the older device cannot meet the requirement, the family should not build its routine around that screen. In that case, one compatible personal device may be the more sensible home for the app.
The app has reached more than a million installs and holds a 4.7 average from roughly eighty-three thousand ratings, with about nine thousand seven hundred written reviews. Those figures suggest that many people have found it worth trying, but popularity does not answer the household-boundary question. I would treat the strong reception as a reason to explore it, not as proof that it will suit every family arrangement.
Small workflow decisions that improve the experience
My first tip would be to start with one financial question instead of attempting to organize an entire household at once. For instance, decide whether the app is being used to understand personal credit-related information, prepare for a monthly review, or support a conversation about a shared expense. A narrow starting point makes it easier to notice whether Credit Genie is genuinely useful.
Second, keep a written household agreement outside the app. It could be as simple as “we discuss shared costs, but personal accounts stay private.” This sounds obvious, yet it prevents memory and assumptions from controlling access. The app should support the agreement, not define it.
Third, review the app at a fixed moment rather than checking it compulsively. A short weekly session can be enough for a coordinator to identify questions and decide what needs discussion. Frequent checking without a decision-making purpose can create anxiety, particularly for someone already worried about credit or bills.
Fourth, do not let a teenager’s first exposure be a crisis. Show the difference between planning a purchase and reacting to a financial problem. If the app is introduced only when money is tight, the young user may associate finance tools with punishment or secrecy instead of learning how to make deliberate choices.
Who should choose something else
I would skip Credit Genie if your main requirement is a fully collaborative household ledger with clearly separated profiles. A spreadsheet or a dedicated shared-budget application may give you better control over individual contributions, permissions, and historical changes. I would also stay with a bank’s own app when the immediate task is checking or managing a specific account securely.
It may also be the wrong choice for someone who dislikes broad finance dashboards and wants one very focused function. More options can be helpful, but they can also make a routine feel less direct. If you only need a basic manual list of bills, a simple notes or spreadsheet workflow may be easier to maintain.
Finally, I would not recommend making it the only source of truth for a household. Financial information should be checked thoughtfully, and important decisions should not depend on one screen being interpreted without context. Credit Genie can help organize attention, but responsibility still belongs to the people managing the money.
My household verdict
After looking at it through a shared-use lens, I see Credit Genie as a useful individual finance app that can contribute to household coordination when its boundaries are agreed in advance. Its free price, Everyone rating, broad finance category, and accessible mobile format make it easy to introduce. Creditly Corp has created something that is more inviting than starting with a blank spreadsheet, and the app’s 2021 release gives it a clear place in the modern mobile finance landscape.
I would recommend it to the household member who wants a central starting point for personal financial checks and is willing to explain relevant conclusions to others. I would not recommend handing one unlocked account to an entire family and calling that collaboration. Privacy, consent, and responsibility need to be decided first.
For a couple, it can support a regular money conversation. For housemates, it is better used by individuals with limited sharing of totals. For parents, it can introduce financial thinking to an age-appropriate discussion without exposing adult details. For a teenager, it should be a learning aid rather than a surveillance tool.
My final judgment is positive but specific: Credit Genie is strongest when one trusted person uses it deliberately and the household coordinates around the results. If you want that kind of personal finance companion, it is worth trying. If you need formal multi-user controls, precise shared accounting, or direct banking operations, I would look to a more specialized alternative instead.
FAQ
What is Credit Genie, and how does it work?
Credit Genie is a personal finance app designed to help users monitor and manage aspects of their financial situation, such as credit information, spending, or access to financial offers, depending on the services available in their region. After creating an account, you may need to provide personal and financial details. Review the app’s terms carefully to understand which features are free, which may involve fees, and how your information is used.
Is Credit Genie a legitimate and safe app to use?
Credit Genie should be downloaded only from the official Google Play Store or Apple App Store, where you can verify the developer, ratings, permissions, and recent user feedback. As with any finance-related application, avoid sharing passwords, banking credentials, or sensitive documents through unofficial links. Before registering, check the privacy policy, security information, customer support details, and whether the app is available legally in your country.
Does Credit Genie provide loans or guarantee approval?
Credit Genie may present financial tools, credit-related information, or loan and cash-advance options, but users should not assume that approval is guaranteed. Eligibility, borrowing limits, interest rates, subscription costs, repayment dates, and other conditions can vary according to your location and financial profile. Read every offer carefully before accepting it, and confirm the total repayment amount rather than focusing only on the advertised advance.
Does Credit Genie affect my credit score?
Using Credit Genie may or may not affect your credit score, depending on the feature you use and whether a credit check is performed. Some services use a soft inquiry that generally does not affect your score, while a lender may conduct a hard inquiry when you apply for credit. The app should explain this before you submit an application, but it is wise to review the disclosure and ask support if anything is unclear.
Are there fees, subscriptions, or repayment requirements in Credit Genie?
Potential costs can include service fees, expedited-transfer charges, membership or subscription payments, interest, late fees, or other lender charges. The exact pricing may differ by country, product, and user eligibility, so do not rely only on promotional descriptions. Before downloading or accepting an offer, inspect the fee schedule, cancellation process, renewal terms, repayment date, and consequences of missing a payment.


